Measure AI's return against a role
AI's return was impossible to isolate while it did scattered tasks. Once it takes on a complete role, you compare it with something you already pay for: what that role costs you.
 El YuntComunicaciones
Ask a CFO how much the last AI tool returned and the answer fills up with caveats. It isn't that the tool did nothing; nobody could isolate what it did, and the value was reported through indicators that never reached the income statement. According to MIT NANDA, in 2025 95 % of organizations reported no measurable return from generative AI.
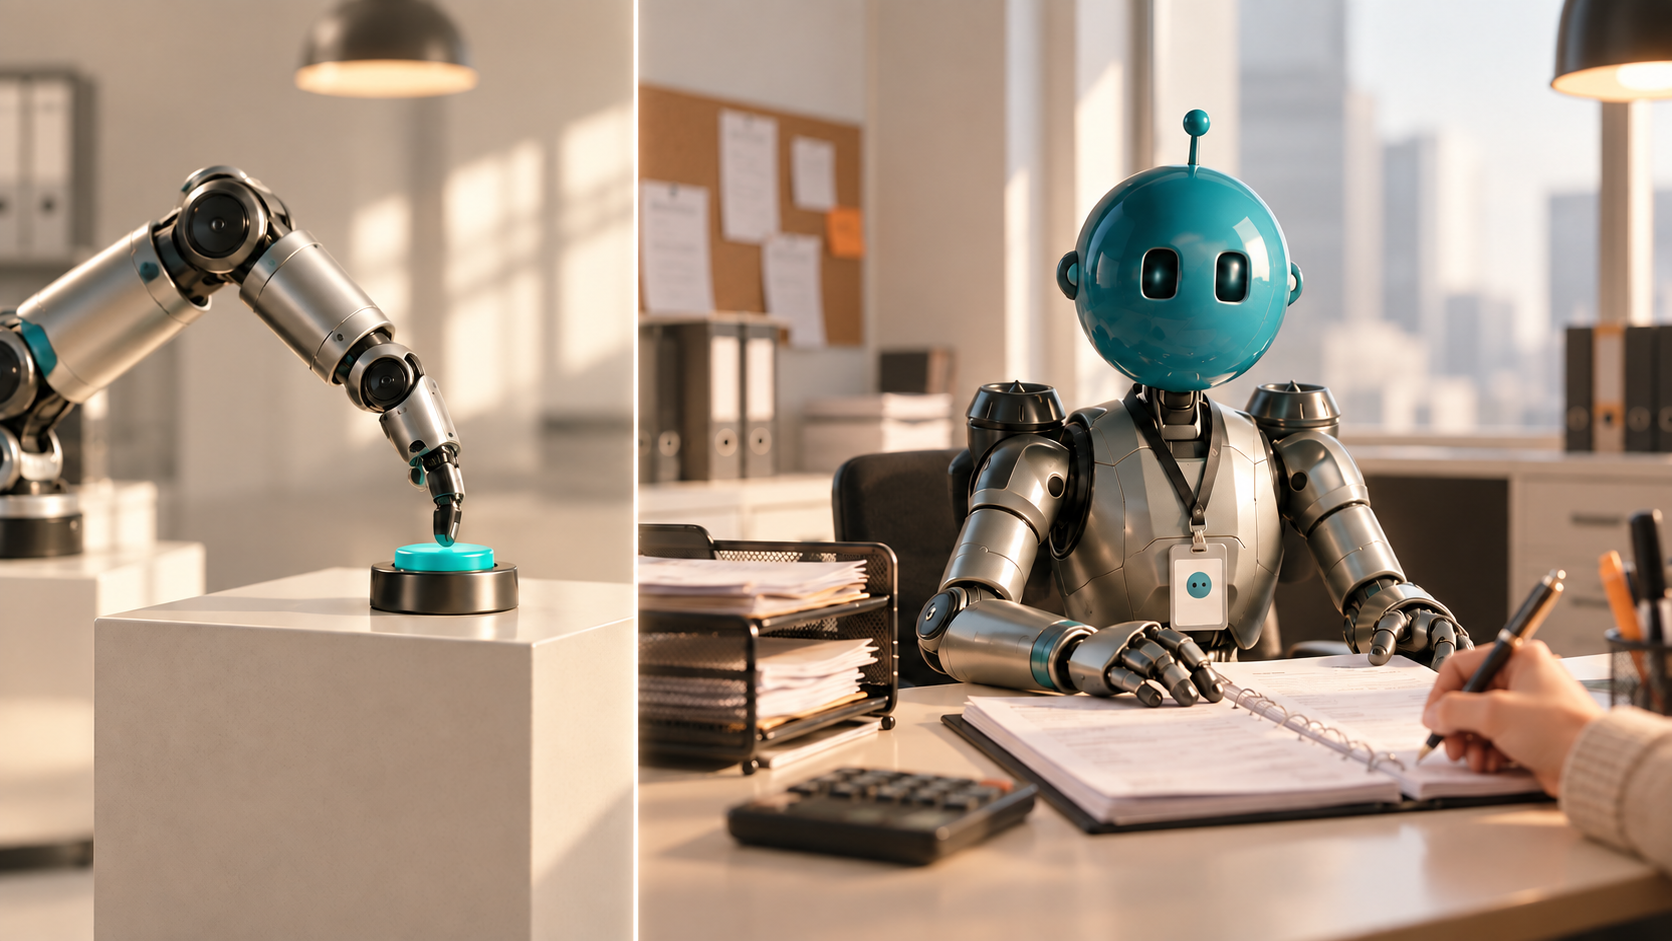
What changed is what you can put in its charge. When AI takes on a complete role instead of a loose task, the return becomes calculable, because a role already has a price: you have been paying it for years on your payroll.
Why task-level AI is so hard to put a number on
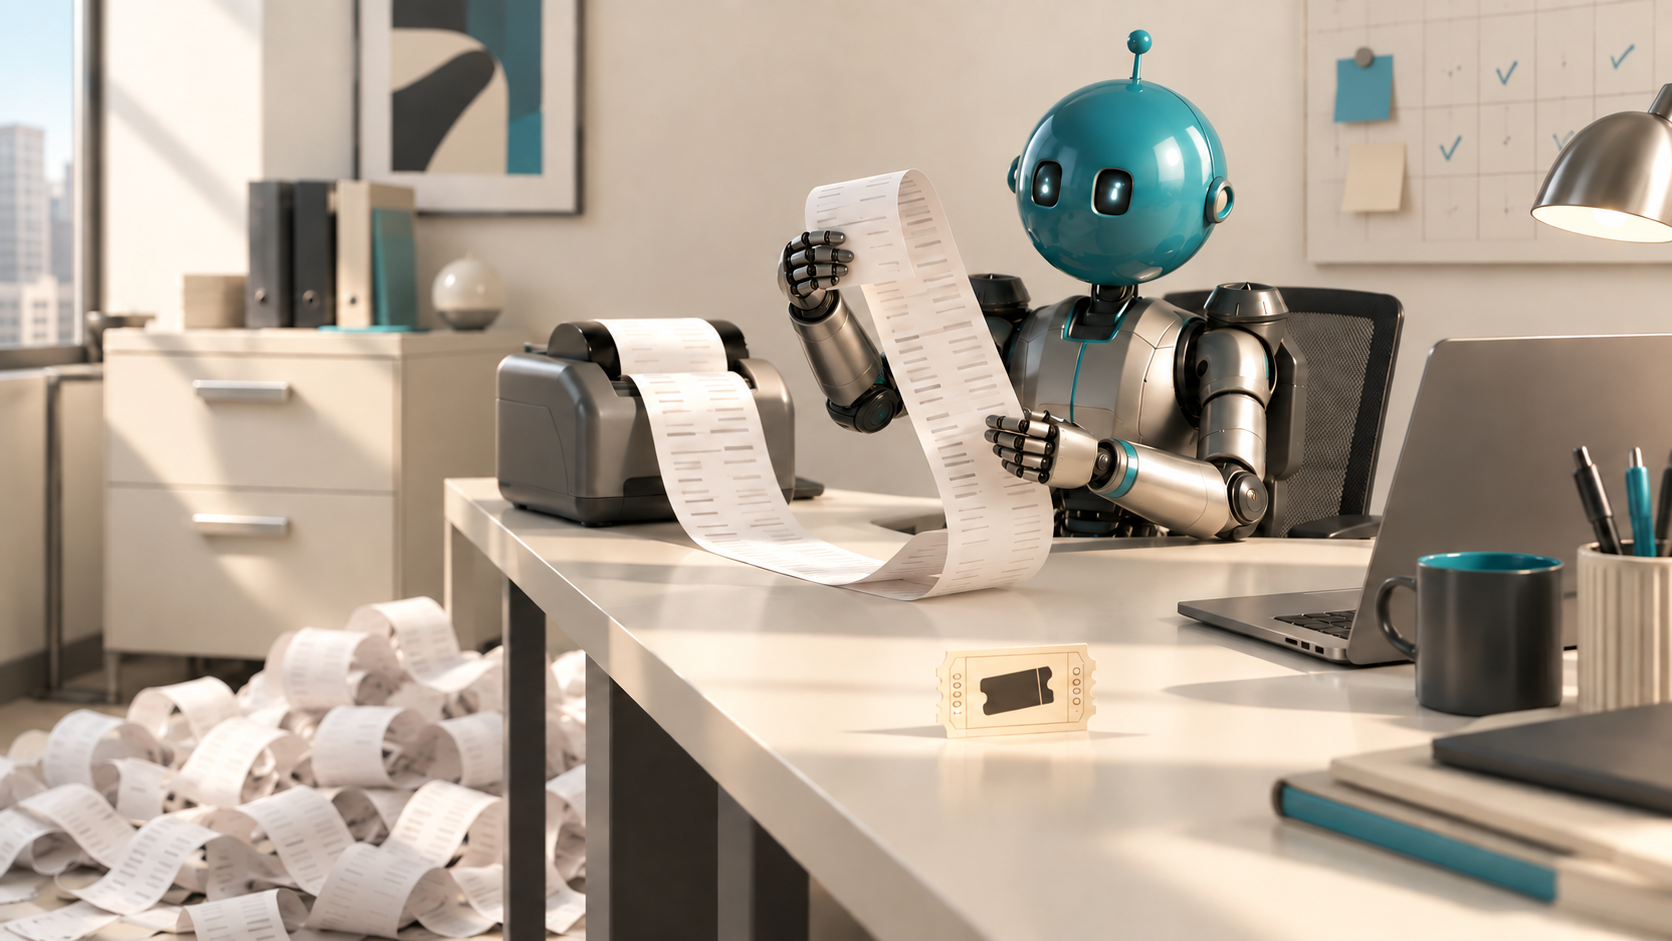
It is hard to attach money to a piece of a process. If an agent extracts the data from an invoice faster, the invoice still has to be matched, approved, posted and reconciled, and the exceptions still need a person. The value leaks away at every handoff, and teams end up reporting hours saved, which rarely land on a financial statement.
A team automates document extraction and reports a 40 % time saving on that step. Finance asks how much that is in money, and the honest answer is that it depends: on whether the rest is still manual, on the exceptions, on whether overtime or hiring was avoided. The step got faster. Whether the operation got cheaper almost never gets answered.
Deloitte called it the AI ROI paradox: investment goes up and the return doesn't show. In Forbes' 2025 survey, fewer than 1 % of executives reported a significant return. The improvement of a task is hard to separate from the operation around it. A role, on the other hand, already has an owner, a cost and an output that gets measured.
A role has a measurable cost. A task rarely stands alone.
When a digital collaborator takes on a role end to end, you are pricing the cost and capacity of an operation. You already know how to measure that baseline: total cost of the role, hours per year, volume processed and committed service level.
The question stops being "how much is faster invoice extraction worth" and becomes "how much does the accounts payable role cost today, what volume does it handle, and how much would it cost to run it another way". That is the practical difference between an agent and a digital collaborator: the agent improves a step; the role is compared against an operation that already exists, and the CFO or COO signs off against an agreed baseline.
The salary is only part of what a role costs
A role does not cost its salary. In the United States, according to the Bureau of Labor Statistics, benefits are close to 30 % of total compensation in the private sector. In Chile the components are different (employer-paid contributions, the legal bonus known as "gratificación", vacation, severance for years of service), but the principle is the same: base salary falls short.
Replacing an experienced person typically costs between 50 and 60 % of their annual salary, according to the Society for Human Resource Management, and a good part of that goes into rebuilding what was never written down: how the work is really done, which walks out the door with the person. The baseline is the recurring cost of keeping the role and what that role knows.
The baseline is agreed before automating
The return becomes hard to calculate when no starting point was ever set. At the start, finance and operations estimate the year's manual effort. Say the role takes four out of every five hours of one person, and the fifth is left for supervising and handling the odd cases.
Later, those estimates are sometimes questioned, even by the people who made them. There is no bad faith: it is natural to remember the work differently once the load has disappeared.
That is why the bar is agreed beforehand. Hours are not enough: it pays to put in writing the volume, the backlog, response times, overtime, seasonal peaks, error rate and expected human oversight. That is the baseline, and not a number rebuilt once the result is known.
The same role can return very different amounts
The return also depends on whether the work is tied to office hours. In high-volume accounts payable, the work does not have to stop when the team goes home. If the invoices are already in the systems, the digital collaborator keeps going at night and on weekends, and capacity goes up without opening another shift or raising cost in the same proportion.
With low volume, the collaborator still leaves a measurable return, but the case rests mainly on hours saved, accuracy, continuity or avoided hiring. That is why two companies automating the same role can end up with very different business cases.
"Positive return from day one": the right claim and the trap
The tempting line is that every digital collaborator pays for itself from day one. Directionally it may be true, but stated as an absolute it is the inflated promise the market has already been burned by, and a good CFO hears it as a sales pitch.
Two things keep the case credible. First, there is a bill beyond the build: operating the collaborator, monitoring it, governing it, maintaining the integrations and paying for model consumption. A business case that ignores those costs is the trap of the pilot that never reaches production, now with a spreadsheet.
Second, the return does not arrive because the demo worked. It arrives when manual effort goes down, when volume grows without headcount growing at the same pace, or when service improves, with a more or less flat operating cost. That way the gap against the total cost of the role widens every quarter. The honest version is also the stronger one, and a CFO can defend it before the board.
Questions a CFO should be asking
How do you calculate the return?
On one side, the role's agreed baseline. On the other, what it costs to build and operate the collaborator. You measure the work avoided and the additional volume absorbed: the role and its output, not a feature against an estimated saving.
What is the baseline, and when does the return show up?
The total cost of the role, agreed before implementation, not the base salary. The return becomes measurable right away and turns positive as the workload grows, as long as you also budget what it costs to operate.
Name the role
If someone asks you for the return on AI and you can't answer without hesitating, you may have bought a task when you needed a role, or never measured what that role cost and produced before automating it.
Name the role, agree on its baseline and measure its cost and its capacity. Then compare it with what it costs and produces with a digital collaborator. The business case does not write itself, but for the first time it can be built on numbers a CFO can defend.
Sources
MIT NANDA, The GenAI Divide: State of AI in Business 2025.
Deloitte, AI ROI: The Paradox of Rising Investment and Elusive Returns (2025).
Forbes Research, 2025 AI Survey.
U.S. Bureau of Labor Statistics, Employer Costs for Employee Compensation (June 2025).
Society for Human Resource Management (SHRM), turnover and replacement cost.